
BUSINESS ASSET INSURANCE

Protect what keeps your business running
You can’t know which of your business assets you might lose, or when. A fire in the workshop, a break-in overnight or a burst pipe over the weekend can damage things your business relies on every day. Business asset insurance lets you choose cover for the assets you actually have, so a setback doesn’t become something your business can’t recover from.
At The Advisers, we take the time to understand how your business works and what it depends on. Then we find cover that fits it, so you’re not paying for things you don’t need or left exposed where it matters.
What business asset insurance can cover
Every business is different, so cover is built around your needs. Depending on the policy, business asset insurance can cover:
Buildings, contents, furnishings, fixtures and fittings
Whether you own your premises or have fitted out a leased space, this covers the physical setting of your business. That includes the building, office furniture, shop fittings, signage and the fit-out you’ve invested in.
Tools, plant, machinery and equipment
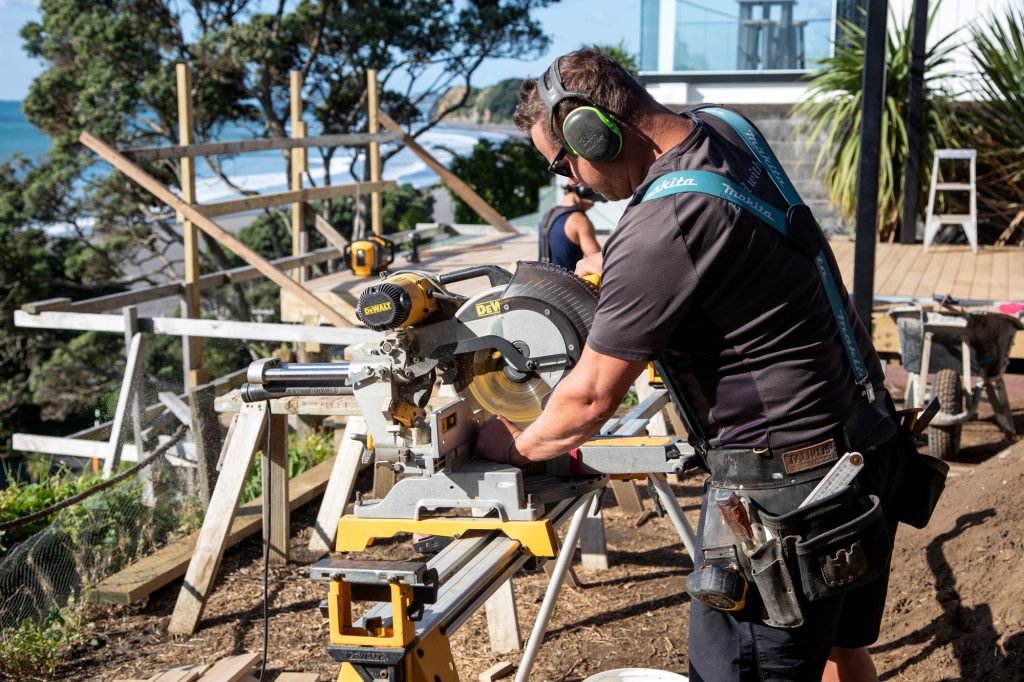
From hand tools and laptops to heavy machinery and specialist equipment, these are often the most expensive assets to replace and the hardest to work without. Cover can apply on-site, and in many cases while tools and equipment are out on the job.
Stock, customer goods and employees’ belongings
Your stock is money tied up on the shelf. Cover can extend to goods you’re holding for customers, such as items in for repair, and to personal belongings your team keeps at work.
Money and other property you’re responsible for
Cash on the premises, takings in transit to the bank, and other property in your care, custody or control can be covered against loss or theft.
Goods in transit anywhere in New Zealand
If you deliver to customers, collect supplies or move equipment between sites, cover can protect goods while they’re being transported around the country.

Why use a broker?
Business insurance policies can be complex, and the details matter. Sums insured, excesses, exclusions and conditions all affect what happens when you claim. As local, independent insurance brokers, we:
- Review your assets and risks so your cover reflects what your business really owns and does
- Compare options from a range of insurers to find the right fit and value
- Explain your policy in plain language, so you know what you’re covered for
- Help when you need to claim, working with the insurer for you so you can focus on running your business
- Check in as your business grows, because new equipment, more stock or a new premises can leave you underinsured
Getting your sums insured right
One of the most common problems we see is underinsurance: assets insured for less than it would cost to replace them today. Rebuilding costs, equipment prices and stock levels change over time. We’ll help you work out realistic sums insured and review them regularly, so your cover keeps up with your business.
FAQ's
It depends on what you do, what you own and who you employ. Most businesses start with cover for their assets, business interruption and public liability, then add things like commercial motor, professional indemnity or cyber cover as needed. We’ll sit down with you, look at your risks and take the guesswork out of it.
If a fire, flood or other insured event forces you to close, business interruption cover helps replace lost income and pay ongoing costs like rent, power and wages. It can also cover the cost of running from a temporary location. For many businesses, it’s the cover that keeps the doors open after a major loss.
Public liability covers you if your business accidentally injures someone or damages their property — say a customer slips on your premises.
Professional indemnity covers you if your advice or professional service causes a client to lose money. If you give advice, design or specialist services, you’ll likely want both.
If you store customer details, take online payments or rely on email and computers, then yes, it’s worth considering. Cyber cover can help with the costs of a data breach, ransomware attack or system outage, including getting expert help to recover.
Yes, whether it’s one ute or a whole fleet. We arrange commercial motor cover across all business vehicle classes, from cars, utes and vans to trucks, buses and forklifts.
We do. We can arrange annual or single-trip cargo cover for goods moving by road, rail, air or sea. We also advise logistics businesses such as freight forwarders, carriers and warehousing operators.
Yes, it’s the best time. Getting the right cover in place early protects your new venture, and we can grow your policies as your business grows. Whether you’re starting out or running a big operation, we’re here to help.
Let’s get you covered
Whether you’re a sole trader with a van full of tools or an established business with several sites, our Advisers are here to help. Contact us today for advice on protecting your business assets.